Crane Bank saga: How a decade-long legal battle is testing Uganda’s banking sector with Sudhir’s Shs884bn claim against dfcu shareholders
Nearly ten years after Crane Bank was taken over, the London trial is therefore about more than the fate of one businessman or one bank. Its eventual outcome could shape perceptions of regulatory accountability, investor protection and the cost of doing business in Uganda's financial sector.
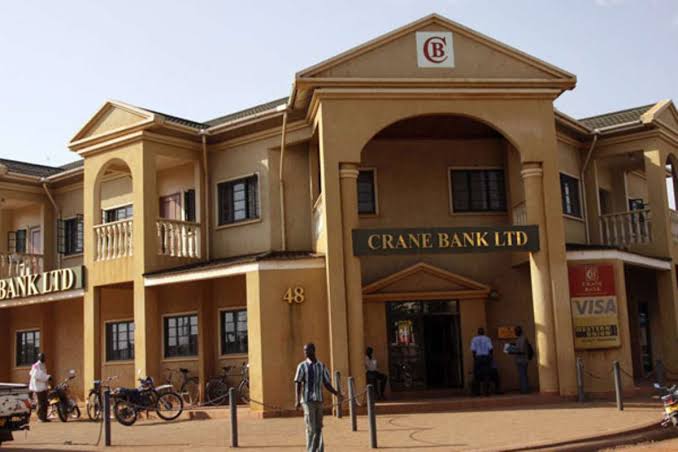
Nearly a decade after the Bank of Uganda took over Crane Bank and transferred much of its business to dfcu Bank, businessman Sudhir Ruparelia’s fight over the institution has reached a defining stage in London, with implications extending beyond the former shareholders and the banks involved.
At stake is a claim exceeding £170 million (about Shs884 billion), with other reports putting the compensation demand at €200 million, approximately $225 million. The dispute is being heard by the Commercial Court of the High Court in London in proceedings that bring together dfcu, its former institutional investors, former banking executives and the Ruparelia family.
The case, which opened in October 2026 and is scheduled to run for approximately 12 to 16 weeks, could influence perceptions of Uganda’s banking regulation, the protection of private investment and the risks facing financial institutions involved in bank acquisitions and resolutions.
For Uganda’s financial sector, the significance is not simply whether Ruparelia wins or loses. It is also about how the court examines the circumstances surrounding one of the country’s most consequential bank interventions and what the outcome could mean for confidence in the regulatory and investment environment.
A bank takeover that became a decade-long dispute
Crane Bank was established by Ruparelia in 1995 and grew into one of Uganda’s prominent indigenous commercial banks, with retail and corporate banking operations across the country.
Its fortunes changed on October 20, 2016, when the Bank of Uganda placed it under statutory management, citing serious financial and regulatory concerns. In January 2017, the central bank transferred selected assets and liabilities to dfcu Bank in a transaction reportedly valued at Shs200 billion, payable over two and a half years.
Ruparelia and the other former shareholders have consistently challenged the takeover and subsequent transfer. They argue that Crane Bank was not valued fairly, that the intervention and disposal were unlawful, and that the transaction deprived them of the value of their investment.
The defendants dispute these allegations. dfcu has maintained that Crane Bank was seriously undercapitalised and experiencing liquidity problems, making intervention necessary to protect depositors and maintain financial stability.
The London proceedings bring together seven claimants, including Crane Bank, Ruparelia, members of his family and former shareholder Tom Mugenga, against 15 defendants. These include dfcu Bank, dfcu Limited, institutional investors and former executives.
The claimants allege that the takeover and subsequent disposal involved unlawful conduct, including conspiracy and dishonest assistance. The defendants deny wrongdoing. These are allegations that the court must determine; they should not be treated as established facts.
The cost of defending a banking transaction
One of the clearest financial consequences of the dispute has already emerged at dfcu.
The litigation has imposed a substantial legal bill on the bank, raising questions about the cost of prolonged disputes arising from bank acquisitions and resolution processes.
According to reported dfcu disclosures, expenditure related to the London litigation increased from Shs42.3 billion in 2024 to Shs76.6 billion in 2025. The legal costs accounted for about 23 per cent of the group’s total operating costs in 2025, according to the reporting.
The pressure became more visible in the first half of 2026, when dfcu reported a net loss of Shs15.8 billion, compared with a profit of Shs34.5 billion in the corresponding period of 2025. Operating expenses rose by 53 per cent to Shs230 billion, while operating income grew by 8 per cent to Shs215.6 billion.
Although the interim accounts did not separately disclose the amount spent on the Crane Bank case during the period, dfcu attributed much of the elevated cost base to the continuing litigation.
This illustrates how a transaction intended to resolve a troubled financial institution can generate prolonged legal and financial exposure for the acquiring bank and its shareholders.
For investors, the case reinforces the importance of understanding the legal risks attached to acquisitions, particularly where the assets being acquired have been transferred through regulatory intervention.
It also raises questions about how banks account for and manage contingent legal liabilities that could affect earnings, capital planning and shareholder returns.
Implications for banking regulation and investor confidence
The case places the Bank of Uganda’s handling of Crane Bank under international judicial scrutiny, although the central bank’s intervention and the subsequent transfer of assets and liabilities are being examined within the legal claims before the London court.
For Uganda’s financial sector, the central issue is the need for regulatory decisions to be legally sound, transparent and supported by proper documentation.
Central banks have a responsibility to intervene when financial institutions threaten depositors or wider financial stability. However, such powers must be exercised within the law and through processes that can withstand scrutiny.
A final ruling could therefore have implications for how future bank resolutions, asset valuations and transfers are structured and documented.
If the claimants succeed, the judgment could expose parties involved in the transaction to substantial financial liability and raise questions about the safeguards applied during the Crane Bank resolution.
If the defendants prevail, it would strengthen their position that the intervention and subsequent transfer were justified, although the wider debate about the handling of the bank may continue.
Either outcome could influence how foreign investors and financial institutions assess the legal and regulatory risks of operating or investing in Uganda.
The dispute also highlights the importance of predictable rules for protecting shareholders, depositors and creditors when a bank enters statutory management or receivership.
A test of Uganda’s investment environment
The international dimension of the case is particularly significant because some of the defendants are linked to major European financial institutions and development finance investors.
The involvement of Dutch and Norwegian-linked investment interests, alongside dfcu and former executives, demonstrates how a domestic banking transaction can create cross-border legal exposure.
For international investors, the case may become a reference point when assessing the risks of participating in Uganda’s financial sector, particularly where investments involve institutions subject to regulatory intervention.
A transparent and credible resolution of the dispute could help reinforce confidence in Uganda’s legal institutions. Conversely, prolonged uncertainty or questions about the handling of the transaction could weigh on perceptions of investment risk.
The case has already passed through several stages in the British courts. In October 2022, the High Court ruled that it lacked jurisdiction to hear the claims. However, the Court of Appeal overturned that decision in July 2023, finding that there were serious issues to be tried. The UK Supreme Court subsequently refused the defendants permission to appeal, allowing the case to proceed.
Those decisions cleared the way for the substantive trial, but they did not determine whether the alleged misconduct occurred.
The wider question: lessons for future bank resolutions
Beyond the compensation being sought, the Crane Bank dispute raises a fundamental question for Uganda’s banking industry: how can regulators resolve failing banks while protecting depositors, maintaining financial stability and ensuring that the rights of shareholders and other stakeholders are respected?
The answer matters because confidence is central to banking. Depositors need assurance that their money is safe, investors need predictable rules, and financial institutions need certainty that transactions undertaken within the regulatory framework will not expose them to years of costly litigation.
For the Bank of Uganda, the dispute underlines the importance of robust valuation procedures, clear records of regulatory decisions and transparent processes when transferring assets and liabilities.
For commercial banks, it is a reminder that the financial consequences of acquisitions can extend well beyond the purchase price, particularly when the transaction is contested in court.
For investors, the case will offer an important test of how Uganda’s banking and regulatory environment handles disputes involving private capital, public authority and financial stability.
Nearly ten years after Crane Bank was taken over, the London trial is therefore about more than the fate of one businessman or one bank. Its eventual outcome could shape perceptions of regulatory accountability, investor protection and the cost of doing business in Uganda’s financial sector.