MTN Uganda’s Shs2.88tn revenue growth faces pressure as costs rise, margins shrink and investment tests profits
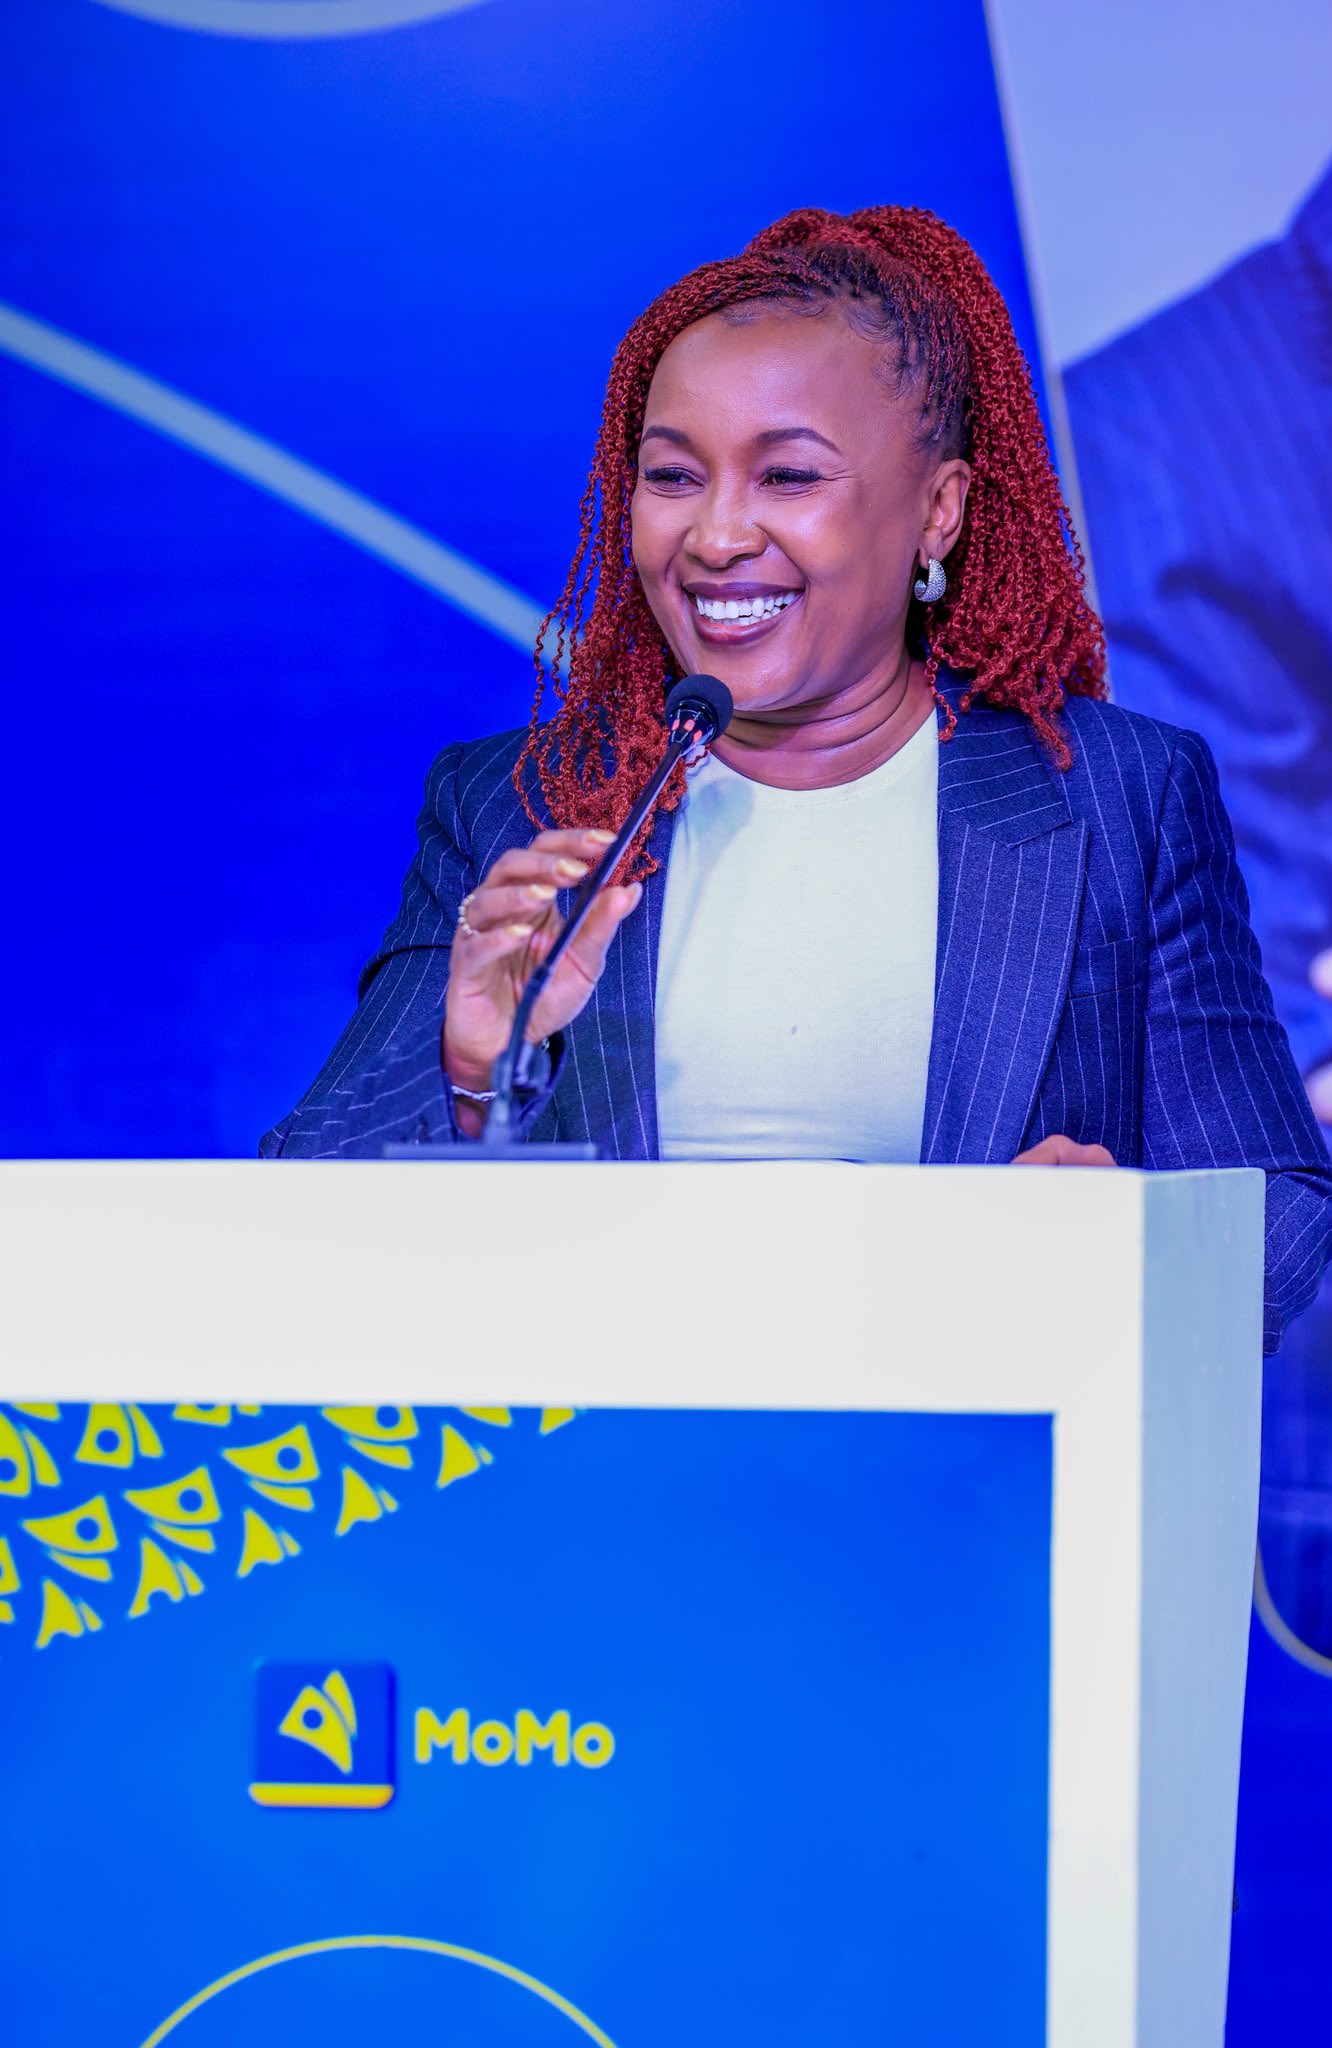
Chief Executive Officer Sylvia Mulinge said the third quarter was marked by macroeconomic and market-specific challenges that moderated growth and commercial momentum.
MTN Uganda is growing its customer base and expanding its digital financial services, but rising operating costs and slowing data revenue growth are emerging as major challenges to sustaining profitability, its nine-month results show.
The telecommunications company recorded an 8.5% increase in total revenue to Shs2.88 trillion for the nine months ended September 30, 2026. Service revenue, which excludes device and SIM card sales, also rose 8.5% to Shs2.84 trillion.
However, the growth in revenue did not translate into a similar improvement in operating profitability. Earnings before interest, tax, depreciation and amortisation (EBITDA) increased by only 3% to Shs1.47 trillion, while the EBITDA margin declined by 2.8 percentage points to 51.1%.
The figures point to a widening gap between revenue growth and the cost of running and expanding the business.
MTN’s total expenses rose 14.6% to Shs1.41 trillion, outpacing revenue growth. The company attributed the pressure partly to higher fuel prices, transport, logistics and supplier costs, as well as accelerated investment in network infrastructure.
The data growth dilemma
One of the most significant developments in the results is the slowdown in data revenue growth during the third quarter.
For the nine-month period, data revenue increased by 12.8% to Shs860.6 billion. Data traffic grew by 31.9%, average consumption per subscriber rose 15.4%, and active data subscribers increased 14.3% to 12.6 million.
Yet data revenue growth slowed to 7.8% in the third quarter, compared with 17.5% in the second quarter.
MTN blamed the moderation partly on unauthorised public Wi-Fi resellers offering unlimited internet packages through business fibre and fixed wireless connections. These services, the company argues, are allowing customers to consume more data without generating corresponding revenue for the operator.
The development highlights a challenge for telecommunications companies: rising internet usage does not automatically translate into higher earnings if customers access connectivity through alternative distribution channels.
MTN says regulatory enforcement against unauthorised public Wi-Fi services began in October 2026. It is also positioning its home broadband business to capture some of the growing demand, with registrations increasing by 58.9% during the reporting period.
Fintech becomes an increasingly important growth engine
While data revenue growth slowed, MTN’s fintech business delivered stronger momentum.
Fintech revenue rose 11.6% to Shs902.8 billion, with growth accelerating to 13.3% in the third quarter. Mobile money revenue increased 11.8% to Shs884.6 billion over the nine months.
The value of mobile money transactions grew 18.3% to Shs166.6 trillion, while transaction volumes increased 10.7% to four billion.
MTN also expanded its fintech distribution network, increasing its agent base by 20.9% to 280,800 and more than doubling its merchant base to 202,800.
Advanced financial services, particularly payments and lending, grew by 26.2% and accounted for 33.2% of fintech revenue.
These figures underline the growing importance of mobile money and digital financial services to MTN’s business model as customers increasingly use the platform for everyday transactions.
The company has added Entebbe Expressway toll payments and travel services through Travel by MoMo, while the MoMo application had grown to more than 832,000 users.
Profit growth masks underlying pressure
MTN reported a 21.2% increase in profit after tax to Shs571.2 billion. However, the improvement was largely influenced by the absence of a Shs111 billion tax settlement recorded in the corresponding period last year.
Excluding that one-off tax settlement, profit after tax would have declined by 1.9%, according to the company.
The third-quarter figures also show signs of pressure. Profit after tax for the quarter was Shs203.8 billion, compared with Shs204.2 billion in the same period last year, a decline of 0.2%.
This suggests that the headline nine-month profit increase does not necessarily reflect a stronger underlying operating performance.
Investment and shareholder returns
MTN is continuing to spend heavily on infrastructure to support future growth. Capital expenditure, excluding leases, increased by 32.6% to Shs397.7 billion.
The investment supported the deployment of 255 new network sites and expansion of its fibre footprint to more than 40,000 kilometres. Fourth-generation (4G) population coverage reached 94%, while 5G coverage increased to 25.6%.
The company also extended its partnership with Starlink into Uganda to serve enterprise customers in areas where conventional network deployment is challenging.
However, the investment programme has affected cash generation. Net cash generated from operating activities declined by 10.2% to Shs429.7 billion, while cash and cash equivalents fell to Shs163.6 billion from Shs383.3 billion at the end of September last year.
The company declared a third-quarter interim dividend of Shs4 per share, amounting to Shs89.6 billion. This brings dividends declared for the nine months to Shs21.25 per share, 3.7% higher than the Shs20.50 declared over the same period last year.
The nine-month payout ratio stood at 83.3% of profit after tax, above the company’s existing 75% dividend payout policy. MTN said the lower quarterly dividend was intended to align shareholder distributions with near-term cash generation while preserving financial flexibility.
A cautious outlook
MTN has lowered its expectations for full-year 2026 service revenue growth, saying it now expects growth to be below its medium-term guidance and broadly in line with the 8.5% achieved in the first nine months.
The company expects its full-year EBITDA margin to be around 50%, reflecting the operating cost pressures.
Chief Executive Officer Sylvia Mulinge said the third quarter was marked by macroeconomic and market-specific challenges that moderated growth and commercial momentum.
The results leave MTN with a balancing act: investing in network capacity to capture rising demand, defending its data business against alternative connectivity providers, expanding fintech services and controlling costs.
Its ability to turn growing data consumption and mobile money activity into stronger revenue and cash generation will be central to its performance in the coming months.