Borrowing to Survive: Uganda’s growing battle against unregulated predatory money lenders and what FDC thinks must be done to stop the credit trap
The FDC official called for stronger enforcement of existing laws against illegal and unregistered money lenders and digital loan applications, particularly those accused of using threats, blackmail and harassment to recover debts.
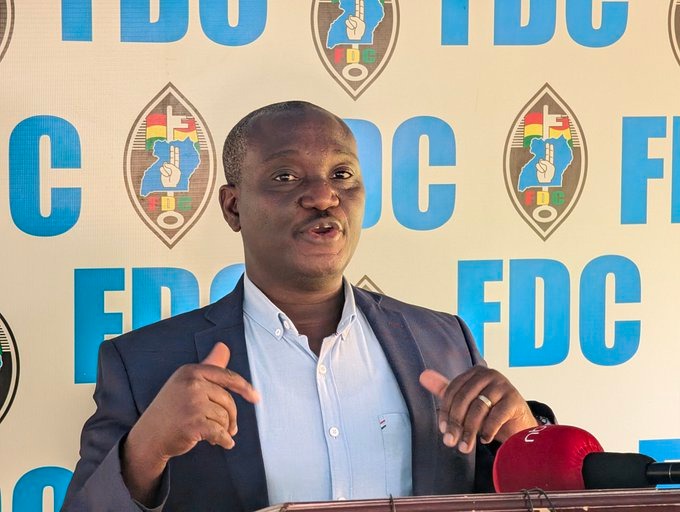
The Forum for Democratic Change (FDC) has called for sweeping reforms to Uganda’s credit system, warning that limited access to affordable formal finance is pushing millions of Ugandans towards money lenders, mobile loan applications and costly asset-financing arrangements.
Speaking at the FDC weekly press conference on Wednesday, August 19, 2026, FDC Vice Chairperson Robert Centinary Franco said the country faces a largely overlooked credit crisis that is exposing households, farmers and young people to predatory lending practices.
Franco said more than half of Uganda’s adult population had borrowed money over the past five years, but many borrowers had not accessed conventional bank credit.
Instead, he said, they had turned to money lenders, mobile lending platforms and asset-financing companies because the formal financial system remains inaccessible to many low-income Ugandans.
“The registered money-lending sector alone turns over more than a trillion shillings a year through roughly 1,800 licensed lenders,” Franco said.
He argued that the scale of the informal and semi-formal lending market demonstrates the extent of the unmet demand for affordable credit.
Property at risk
Franco raised concerns about lending practices in communities, particularly cases where borrowers allegedly surrender land, homes, livestock or other assets after failing to meet repayment obligations.
He said some borrowers are persuaded to surrender national identity cards or sign documents presented as loan agreements, which may instead be structured as sale agreements for property.
“When they default, there is therefore no conventional loan to dispute,” he said.
The FDC official called for stronger enforcement of existing laws against illegal and unregistered money lenders and digital loan applications, particularly those accused of using threats, blackmail and harassment to recover debts.
He also proposed stronger protection of national identity cards and land titles against being used as informal or unregulated collateral outside registered lending arrangements.
Boda boda riders face financing pressure
The FDC also highlighted challenges facing Uganda’s large motorcycle taxi sector, commonly known as boda boda, which has become a major source of employment for young people unable to find jobs in the formal economy.
Franco said many riders begin their businesses without owning motorcycles outright, instead acquiring them through asset-financing companies and micro-credit firms under hire-purchase arrangements.
Under such arrangements, riders typically make an initial deposit followed by regular instalments. Failure to meet payments can result in repossession of the motorcycle, sometimes after the rider has already paid a substantial amount.
Franco said repossession can immediately eliminate a rider’s source of income.
“When the bike is taken, the rider’s income stops the same day,” he said.
He warned that some young people who lose their motorcycles and are unable to regain them can become vulnerable to criminal activity.
The FDC is proposing the establishment of a Boda Boda Savings and Protection Cooperative Scheme to give riders access to savings, medical insurance, pension and accident protection while reducing dependence on asset-financing companies as the primary route into the sector.
Farmer banks proposed
The opposition party also wants government to establish specialised farmer banks within agricultural zones to improve access to credit for farmers.
The proposed institutions would provide financing for land, seeds, pesticides, irrigation and other agricultural investments on terms that are more affordable than those offered by informal lenders.
The proposal is based on the argument that agriculture remains a major source of livelihoods but many farmers lack the collateral and financial records required to access conventional bank loans.
Franco said affordable agricultural credit could help farmers invest in productivity rather than resorting to expensive short-term borrowing.
Revival of Cooperative Bank
The FDC further proposed restoring the Cooperative Bank and recovering what it described as stolen cooperative assets.
The party argues that rebuilding a cooperative-based financial institution would provide an additional formal credit channel for communities and cooperative members who are currently relying on money lenders.
It also wants leadership Savings and Credit Cooperative Organisations (SACCOs) established at parish, sub-county and district levels, supported by direct government capitalisation.
According to Franco, locating such financial structures closer to communities would make savings and credit services more accessible to ordinary Ugandans.
Cheap capital for vulnerable groups
The FDC also called for affordable capital with minimal collateral requirements for women, youth, persons with disabilities, elderly people, pensioners and veterans.
The party argues that conventional collateral requirements exclude many people who have viable economic activities but lack formal property ownership.
Franco said the government’s response should focus on closing the credit-access gap rather than simply dealing with the consequences of debt distress.
“There is one condition that makes predatory lending possible: poor access to affordable credit,” he said.
He argued that Ugandans turn to money lenders primarily because they are accessible when formal credit is not.
The FDC’s proposals therefore seek to expand formal and community-based financing channels while strengthening consumer protection and regulation of lenders.
Closing Uganda’s credit gap
The debate over access to affordable finance comes as Uganda seeks to expand private sector investment, employment and household incomes.
For the FDC, however, expanding access to credit must go hand in hand with protection against abusive lending practices.
The party’s proposals include cheaper capital, farmer-focused financial institutions, stronger cooperative finance, community SACCOs, protection schemes for boda boda riders and tougher enforcement against illegal lenders and abusive digital loan platforms.
The broader objective, Franco said, is to build a financial system that enables Ugandans to borrow for productive purposes without placing their homes, land, livelihoods and personal security at excessive risk.
The FDC contends that unless affordable formal credit reaches communities, the gap will continue to be filled by lenders operating at higher costs and, in some cases, outside effective regulatory oversight.