Central bank licenses four more large SACCOs as regulatory push gains momentum
The four institutions receiving licences now join the first group of large SACCOs operating under BoU's regulatory framework.
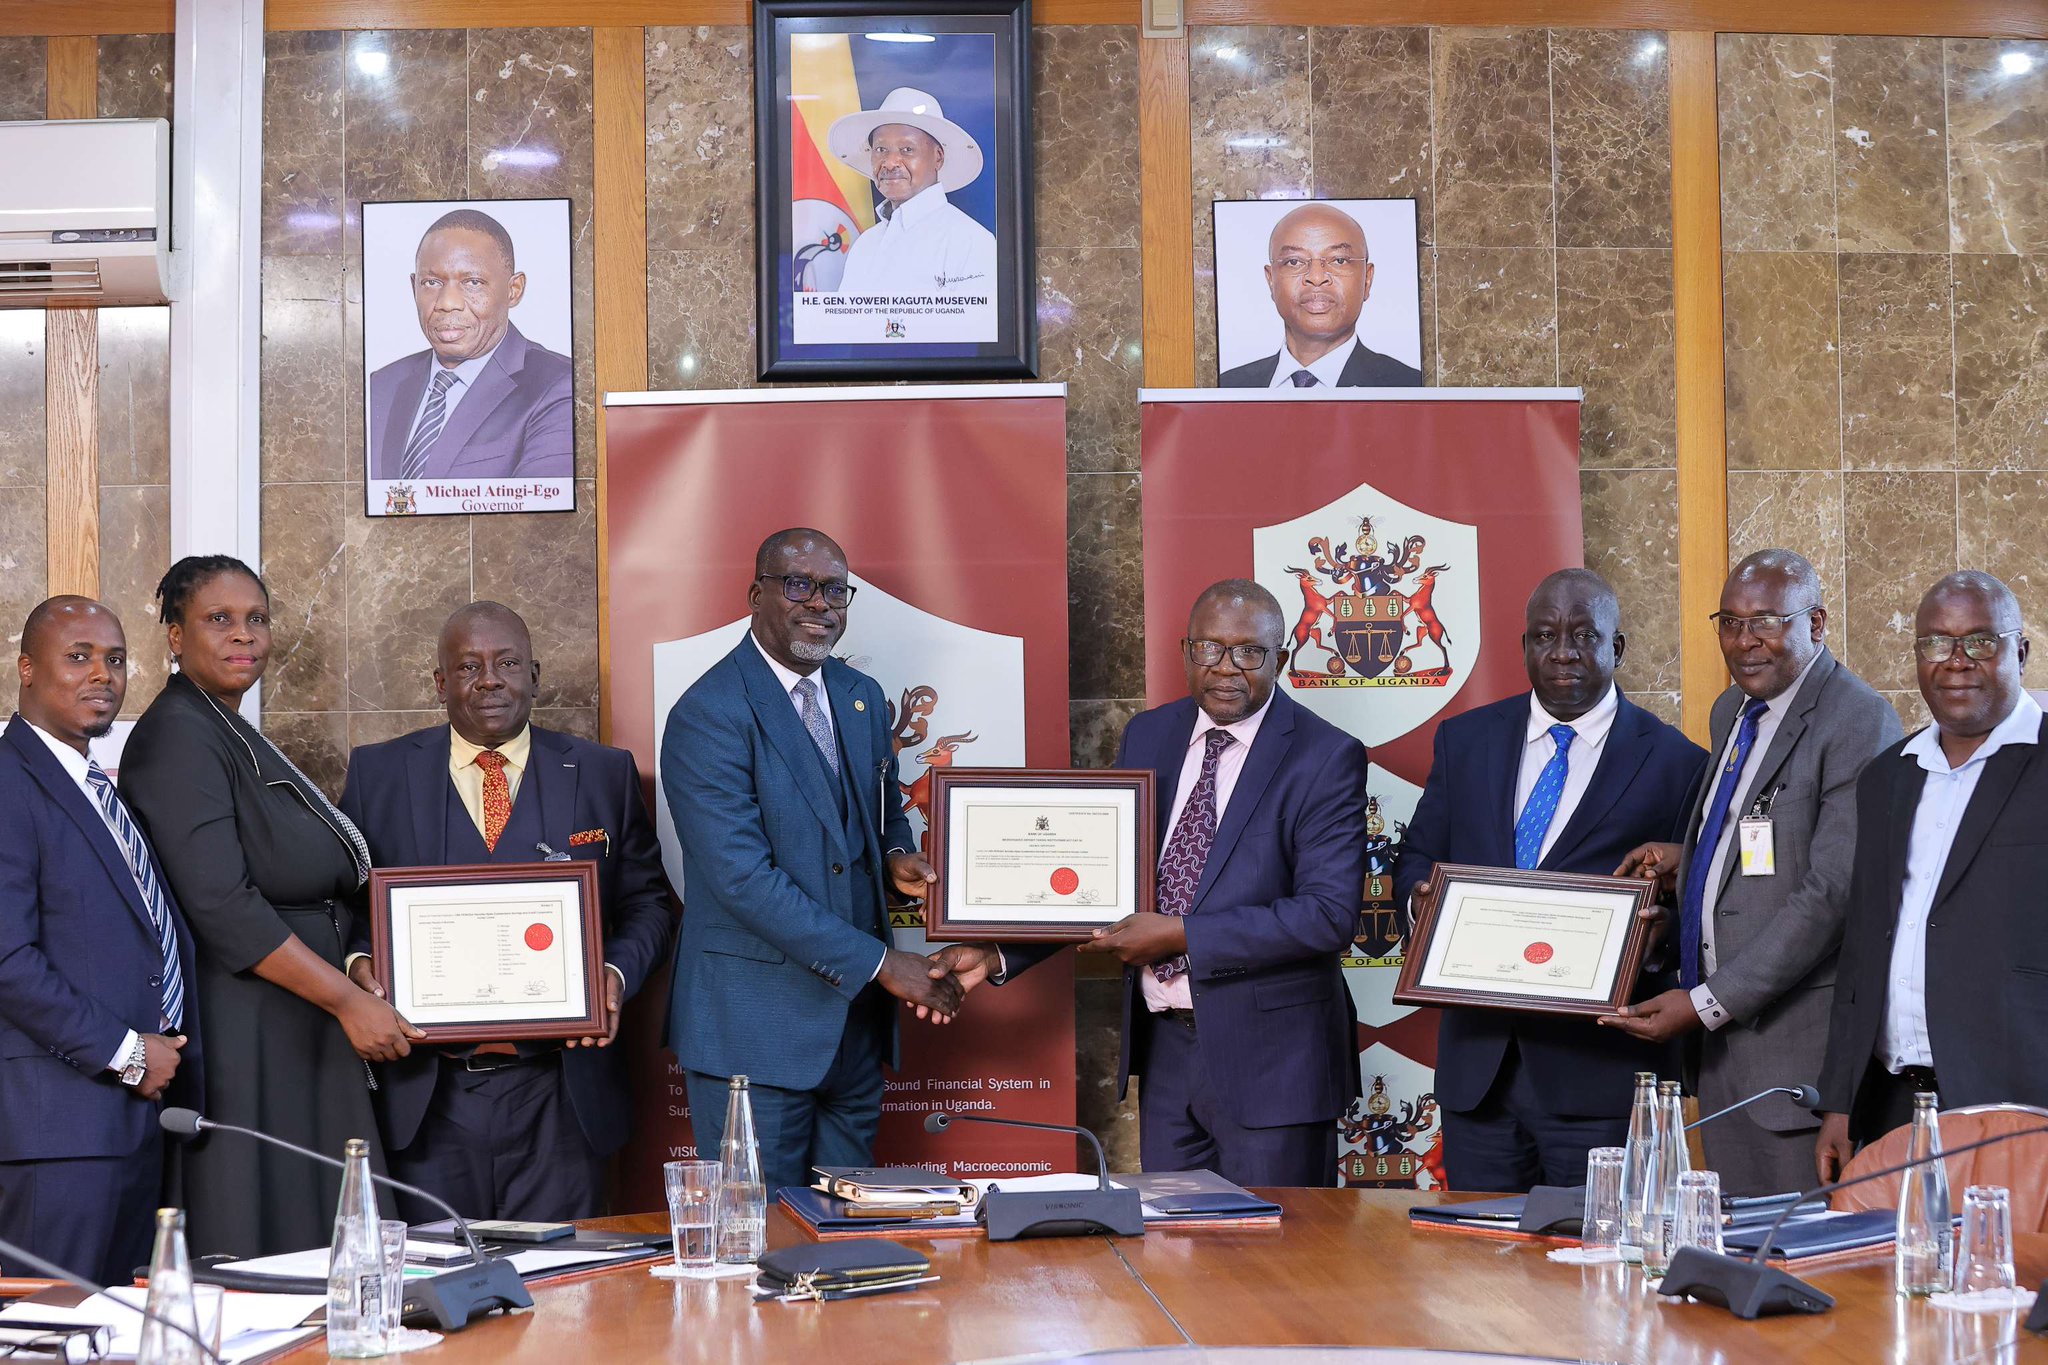
The Bank of Uganda (BoU) has licensed four more large Savings and Credit Cooperative Organisations (SACCOs). This expands the number of large SACCOs under its prudential supervision to ten. The central bank is also accelerating it’s efforts to strengthen governance and protect members’ savings.
The newly licensed institutions are Uganda National Bureau of Standards (UNBS) Staff Cooperative Savings and Credit Society Limited; Kibaya Youth Development Cooperative Savings and Credit Society Limited in Mbarara; CBS PEWOSA Nsindika Njake Eyeeterekera Savings and Credit Cooperative Society Limited; and Mateete Savings and Credit Cooperative Society Limited in Sembabule.
The licences were formally handed over on Wednesday by David Kalyango, BoU Executive Director for Supervision and Regulation, who represented Governor Michael Atingi-Ego.
Kalyango congratulated the boards, management, staff and members of the four SACCOs, describing licensing as an important milestone in the development of Uganda’s cooperative financial sector.
From cooperative societies to regulated financial institutions
The latest licences come as BoU intensifies the transition of large SACCOs into a formal prudential regulatory framework.
The four institutions were licensed under the Microfinance Deposit-Taking Institutions Act, Cap. 58, and the Microfinance Deposit-Taking Institutions (Registered Societies) Regulations, 2023.
The framework is intended to facilitate the growth of SACCOs while preserving their cooperative business model.
The latest approvals take the number of BoU-licensed large SACCOs to 10, while more than 35 applications are at the final stages of review, according to Kalyango.
The acceleration comes after months of debate over the regulation of large SACCOs, with the central bank seeking to bring institutions holding significant member savings under stronger prudential oversight.
BoU recently extended the compliance deadline for eligible SACCOs to 31 March 2027, amid consultations with stakeholders and efforts to address concerns about the transition.
Protecting the savings pool
For BoU, the licensing drive is fundamentally about strengthening confidence in a sector that has become an increasingly important source of finance for households, farmers, traders and small businesses.
Kalyango said effective licensing and proportional regulation should give SACCO members greater assurance that their savings are protected, including through enhanced safeguards such as deposit protection.
Regulation is also expected to improve governance, accountability, risk management, financial reporting and internal controls, creating stronger and more resilient institutions.
“Trust is the foundation of sustainable financial services,” Kalyango said. He urged the newly licensed institutions to maintain sound controls, accurate records, ethical conduct and timely disclosure.
The new regulatory status, however, comes with greater responsibilities.
Boards are expected to provide effective oversight, while management must maintain adequate capital and liquidity buffers, manage credit risks and submit accurate regulatory returns.
BoU also wants SACCOs to match their growth with investment in people, technology, systems, controls and customer service.
Cheaper credit and deeper financial inclusion
The central bank sees well-governed SACCOs as more than savings institutions.
Because they have close relationships with households, farmers, traders, small businesses and organised groups, licensed SACCOs can provide tailored financial products to communities that may remain underserved by conventional banks.
Kalyango said prudently managed SACCOs can mobilise savings, provide responsible credit and finance investment, helping more Ugandans participate in the formal money economy.
He also encouraged SACCOs to retain more of their surpluses to strengthen their lending pools and potentially provide credit to members at lower interest rates.
The message is particularly significant as Uganda seeks to expand affordable financing for productive sectors and increase private investment.
Access to government-backed financing
Licensing could also open additional financing opportunities for the institutions.
BoU said regulated SACCOs are eligible for subsidised funding through the Agricultural Credit Facility (ACF) and the Small Business Fund, providing avenues to expand affordable financing for agriculture and businesses.
This creates a potential link between stronger SACCO regulation and the Government’s broader economic transformation agenda.
Well-capitalised and properly governed SACCOs can potentially serve as channels through which affordable finance reaches farmers, small enterprises and organised community groups—particularly outside major urban centres.
Deadline approaches
Despite the progress represented by the four new licences, the wider licensing exercise remains substantial.
BoU said more than 35 applications are still undergoing final review and urged all eligible but unlicensed SACCOs to complete the process before the 31 March 2027 compliance deadline, which the central bank said will not be extended.
The licensing campaign has followed a prolonged discussion between BoU and the cooperative movement over the appropriate regulatory framework for large SACCOs.
Cooperative leaders have argued for a harmonised approach that recognises the ownership and governance structure of SACCOs, while BoU has maintained that large institutions handling significant savings require effective prudential supervision. Parliament has since facilitated discussions on possible legal amendments to harmonise the regulatory framework.
The four institutions receiving licences now join the first group of large SACCOs operating under BoU’s regulatory framework.
For the wider sector, their transition offers an early test of whether stronger supervision can be combined with the cooperative model to deliver greater trust, safer savings and more affordable credit to Uganda’s underserved households and businesses.